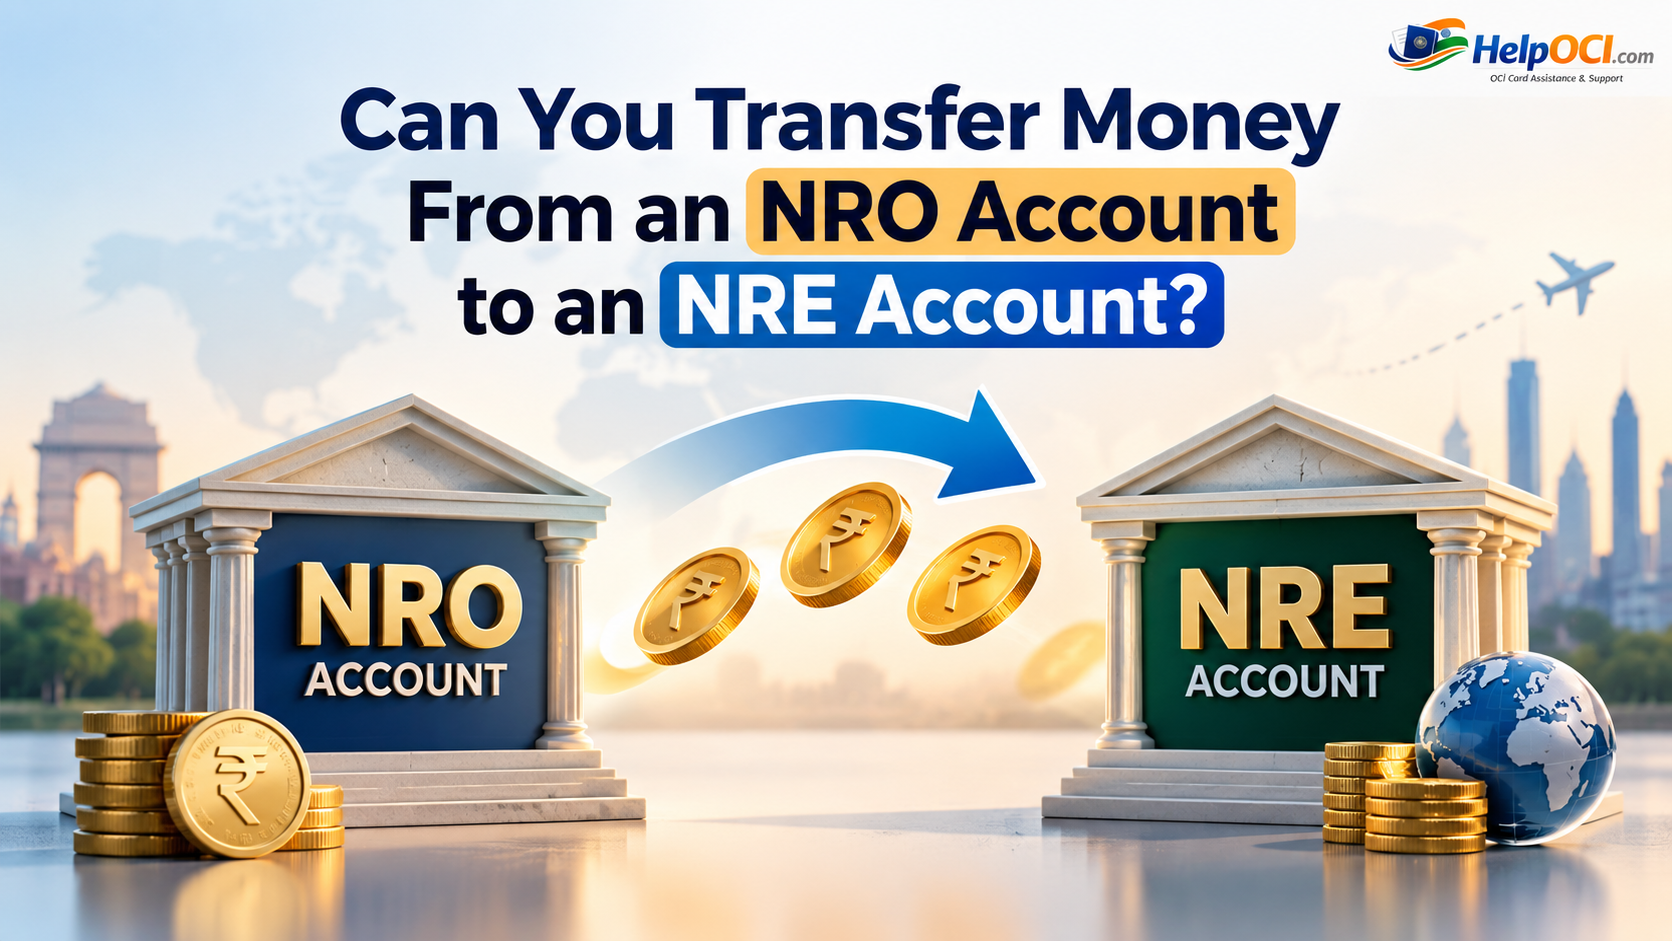
Yes, it is possible to transfer money from an NRO account to an NRE account, but the transfer is subject to specific RBI regulations, tax requirements, and documentation. Many Non-Resident Indians (NRIs) have questions about moving funds between these two account types, especially when they want to make eligible funds repatriable.
Understanding the rules set by the
Reserve Bank of India (RBI) and the
Foreign Exchange Management Act (FEMA) is important for a smooth transfer.
This guide explains the conditions, limits, procedures, and documentation involved in transferring money from an NRO account to an NRE account.
Understanding NRO to NRE Transfers
The ability to transfer funds from a Non-Resident Ordinary (NRO) account to a Non-Resident External (NRE) account can be useful for NRIs managing their finances in India. An NRO account is generally used to hold income earned or received in India, such as rent, dividends, pension, or interest.
An NRE account, on the other hand, is primarily used to hold foreign earnings in India and offers full repatriability, subject to applicable rules.
When eligible funds are transferred from an NRO account to an NRE account, the money becomes part of the NRE account balance and can generally be repatriated outside India. However, the transfer is subject to applicable tax compliance, documentation, and the prescribed limits under RBI regulations.
Benefits of Transfer Money from NRO to NRE
Full Repatriability
One of the main benefits is that funds held in an NRE account are generally freely repatriable. After eligible funds are transferred from your NRO account to your NRE account, they can generally be transferred to your overseas bank account without the same repatriation restrictions that apply to NRO funds.
Tax-Free Interest
Interest earned on an NRE account is generally exempt from Indian income tax, subject to the applicable conditions. This can make an NRE account useful for holding eligible repatriable funds.
Simplified Fund Management
Moving eligible funds into an NRE account can make it easier to manage repatriable money. It also allows NRIs to keep funds intended for overseas use separate from income that remains in their NRO account.
Currency Management
Both NRO and NRE accounts are maintained in Indian Rupees. Transferring funds from NRO to NRE does not itself convert the money into foreign currency. However, the NRE account provides a convenient way to hold repatriable INR funds and later convert them into foreign currency when remitting money overseas.
Conditions for Transfer Money from NRO to NRE
Yes, you can transfer eligible funds from an NRO account to an NRE account, provided the applicable RBI and FEMA conditions are satisfied. For the step-by-step process, see our guide on [
How to Transfer Funds from NRO to NRE Account]. RBI permits NRIs to transfer funds from an NRO account to an NRE account within the overall
USD 1 million per financial year facility, subject to applicable taxes and other conditions.
The transfer is not governed by the USD 250,000
Liberalised Remittance Scheme (LRS) limit, as LRS applies to resident individuals. The bank may require documents confirming the source of funds and evidence that applicable tax obligations have been addressed before processing the transfer.
Depending on the nature of the transaction, the bank may also request tax forms, certificates, bank statements, or other supporting documents.
Situations Requiring Documentation and Tax Compliance
Proceeds from Property Sale
If you have sold a property in India and the sale proceeds are deposited into your NRO account, the bank may require documents related to the property transaction and applicable tax compliance before allowing the funds to be transferred to your NRE account.
Accumulated Rental Income
For funds accumulated from rental income in your NRO account, you may need to provide documents showing the source of the income and the relevant tax position. This could include income tax records, bank statements, or other documents requested by the bank.
Inherited Assets or Funds
If inherited money or assets are credited to your NRO account, the bank may request documents establishing the inheritance, such as a will, succession certificate, probate documents, or other applicable legal records. Additional tax or compliance documents may also be required depending on the circumstances.
Maturity Proceeds of Investments
When investments held through an NRO account mature, such as fixed deposits or certain investments, the proceeds may be credited back to the NRO account. To transfer these funds to an NRE account, the bank may ask for investment statements and documents confirming the source of funds and applicable tax compliance.
Conclusion
In summary, NRIs can transfer eligible funds from an NRO account to an NRE account, subject to RBI/FEMA regulations, applicable taxes, documentation, and the prescribed transfer limit. The applicable facility allows eligible NRO funds to be transferred within the
USD 1 million per financial year limit, rather than the USD 250,000 LRS limit.
The documents required can vary depending on the source and nature of the funds. Forms such as
Form 15CA and Form 15CB may be required in certain circumstances, but they are not automatically mandatory for every NRO-to-NRE transfer. Checking the requirements with your bank or tax professional before initiating a large transfer can help avoid delays.
Comments